Report: Demand Remains Strong
for U.S. Construction
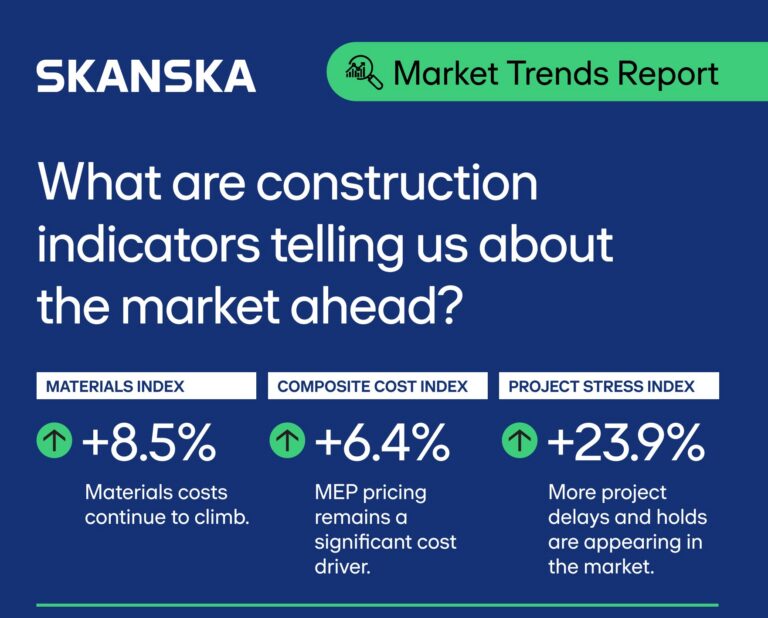
NEW YORK—Skanska recently released Summer 2026 Construction Market Trends Report found underlying construction demand remains stronger than anticipated, but growth continues to be highly concentrated across a handful of sectors. Those growth sectors include data centers, infrastructure, power generation, advanced manufacturing, pharmaceutical production and select healthcare markets attracting significant capital investment.
“As we move into the second half of 2026, the construction market is being defined less by concerns for lack of demand and more by the industry’s capacity to deliver,” said Steve Stouthamer, Executive Vice President of Project Planning at Skanska USA Building. “Data center, power, advanced manufacturing and life sciences investment continues to create significant opportunities, but labor availability, power constraints, equipment lead times and material costs are continuing to challenge owners and contractors. In this environment, advanced planning and early procurement are increasingly critical to keeping projects on schedule and managing cost exposure.”
The report highlights an increasingly uneven market, with robust project pipelines in technology and infrastructure-related sectors contrasting with comparatively subdued activity in office, retail, higher education and other commercial development. Healthcare and higher education markets remain more mixed nationally, with activity varying by regional population growth and policy. Financing conditions are also continuing to pressure certain private developments, while sectors supported by major infrastructure and technology investment maintain stronger momentum.
Among the report’s key highlights include:
- Construction activity remains strong but increasingly concentrated across high-growth sectors: Data centers, infrastructure, power generation, advanced manufacturing, pharmaceutical production and select healthcare markets continue to attract significant investment, while office, retail, higher education and other commercial sectors remain comparatively subdued. Healthcare and higher education activity remains mixed across the country, with regional population growth and policy shaping market conditions.
- Data center construction remains the fastest-growing segment of U.S. commercial construction, with data centers accounting for approximately 5.4% of private nonresidential building construction spending in 2025, up from approximately 1.7% in 2019. Annual U.S. data center construction spending is expected to exceed $100 billion by 2030, more than doubling current levels.
- Capacity constraints across labor, power and equipment continue to challenge project delivery. Power availability, skilled labor, municipal concerns and equipment lead times remain key constraints on data center development and other high-growth sectors.
Published: September 9, 2026.